
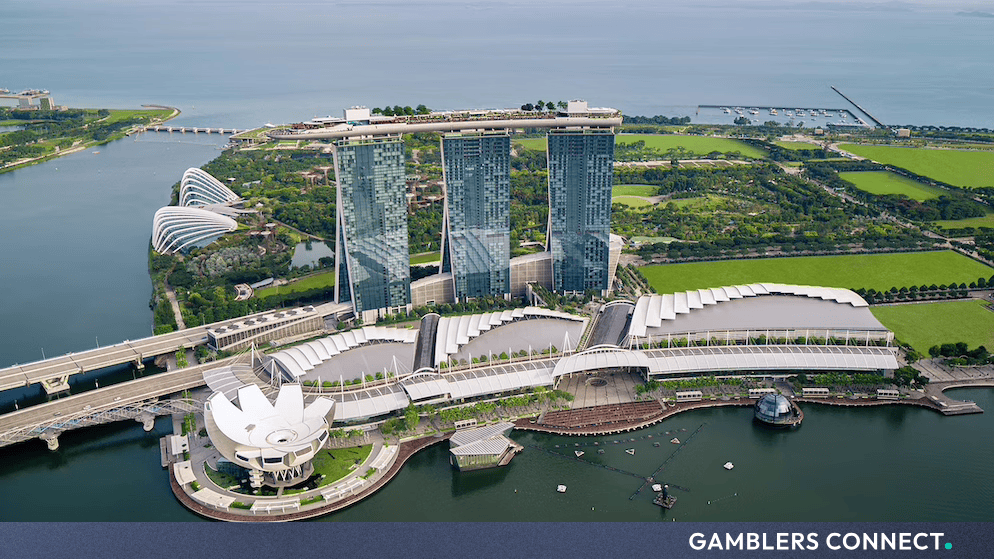
Marina Bay Sands (MBS) reported adjusted property EBITDA of $590 million for Q3 2026, representing a 20.6% decrease compared to $743 million during the same period in 2025.
According to parent company Las Vegas Sands’ earnings disclosure filed on October 21, the earnings contraction was primarily driven by a lower non-rolling chip win percentage that weighed on casino results, offsetting gains in mass table activity and stronger hotel room rates.
Net revenue at the Singapore integrated resort declined 9.9% year-on-year to $1.29 billion, down from $1.44 billion. Casino revenue dropped 14.9% to $916 million, causing the property’s EBITDA margin to narrow by 6.1 percentage points to 45.6%.
Lower table hold weighs on casino results
Detailed operational breakdowns highlight that non-rolling chip drop increased 12.6% to $2.87 billion, but the win percentage fell sharply to 18.7%, down from 24.5% a year earlier. This reduction in the proportion of funds retained at the tables, rather than a drop in mass betting volume, was central to the weaker gaming results.
Slot handle increased 2.1% to $6.54 billion, with hold remaining steady at 4.4%. Premium gaming experienced a contraction in rolling chip volume, which fell 7.1% to $8.43 billion, while its win rate decreased from 4.84% to 4.53%. Las Vegas Sands estimated that EBITDA would have been $4 million higher at $594 million if rolling chip hold had matched its theoretical value of 4.6%, contrasting with the previous year’s positive variance of $43 million. Furthermore, table games wins per unit per day dropped from $21,380 to $17,920.
Hotel revenue rises with firmer room rates
In contrast to the gaming headwinds, the resort’s non-gaming operations delivered strong results. Total room revenues increased to $162 million from $154 million, supported by a high room occupancy rate of 95.8% and an average daily rate ranging between $982 and $1,038, pushing revenue per available room to $994.
Food and beverage revenues climbed to $104 million, mall revenues remained steady at $70 million, and convention, retail, and other contributions rose 2.4% to $42 million. For the first nine months of 2026, MBS achieved net revenues of $4.16 billion, a 4.4% increase, though adjusted property EBITDA dipped 2.3% to $2.07 billion. Ratings agencies have consistently highlighted the resort’s robust cash generation as key support for the wider group, with Moody’s maintaining a stable outlook for Las Vegas Sands despite substantial ongoing development commitments.
Parent reports lower consolidated EBITDA and expansion funding
At the group level, Las Vegas Sands reported net revenue of $3.22 billion and adjusted property EBITDA of $1.12 billion, down from $1.34 billion previously. The company’s Macao operations contributed $529 million amid a 3.8% decline in gross gaming revenue across that market during the third quarter. Demonstrating ongoing shareholder commitment, LVS repurchased $950 million worth of its stock during the quarter and raised its recurring dividend by 20% for 2027 to $1.44 per share annually.
Capital expenditures at Marina Bay Sands reached $121 million during the quarter, backed by $4.57 billion available through a delayed draw term loan facility designated for the resort’s major expansion project. Chairman and CEO Patrick Dumont characterized the Singapore performance as solid despite the earnings dip, emphasizing that the ongoing expansion will introduce additional suite capacity and a state-of-the-art arena designed to become a premier regional entertainment venue.